
A software subscription can look affordable until you add setup, training, integrations, and the time needed to maintain it. Equally, a more expensive system may justify its cost if it removes recurring expenses or supports profitable additional work.
The challenge is identifying what the software actually changes.
Learning how to calculate the return on investment of business software starts with comparing its full costs against measurable benefits over a defined period. It also requires distinguishing money saved from staff time released.
This guide explains the formula, shows a worked example, and outlines how to build an estimate you can check against actual results.
What Is Business Software ROI?
Return on investment, or ROI, expresses the net benefit of an investment relative to its cost.
The Australian Government’s business guidance describes ROI as net investment profit divided by investment cost, expressed as a percentage.
For a practical software business case, use:
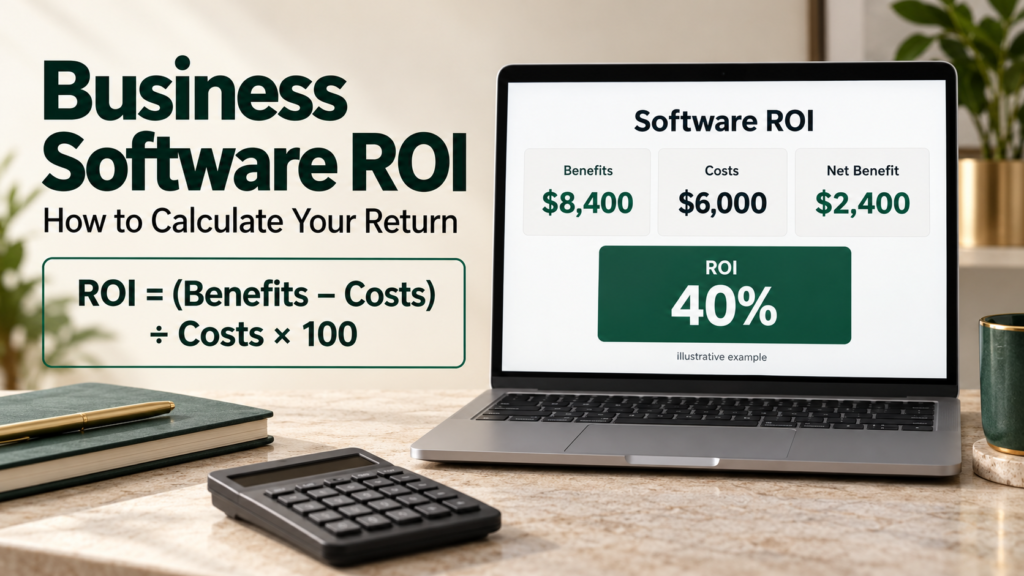
Software ROI (%) = [(Total measurable benefits − Total software-related costs) ÷ Total software-related costs] × 100
For example, if software produces $9,000 in measurable benefits and costs $6,000 over the same period:
ROI = [($9,000 − $6,000) ÷ $6,000] × 100 = 50%
The net benefit is $3,000. A 50% ROI means the estimated net benefit equals half the investment cost over the stated period.
It does not mean revenue increased by 50%, and it does not guarantee future performance.
Define What Your Calculation Includes
There are two useful perspectives:
| Perspective | What it measures |
|---|---|
| Cash-based ROI | Additional cash contribution and spending avoided, compared with additional cash costs |
| Broader economic ROI | Cash effects plus justified values for internal resources and productive capacity |
Both can be useful. Label them clearly and apply the chosen perspective consistently to benefits and costs.
Do not describe a broader productivity estimate as money that will necessarily appear in the bank.
Step 1: Define the Decision and Comparison Period
Before collecting numbers, state what you are evaluating.
For example:
“Should we replace our current invoicing process with a new system over the next 12 months?”
Compare the proposed setup with what would reasonably happen without it. That might be keeping the existing software, improving a manual process, or choosing another product.
A 12-month period is useful for an initial view, but a longer period may better reflect a significant implementation.
Use the same period for costs and benefits. Do not compare three years of benefits with one year of subscription fees.
Account for Implementation Timing
If deployment takes two months, full benefits may not begin immediately.
Build the estimate month by month when timing matters. Include any period when you must pay for both old and new systems.
For longer investments, consider discounted cash flow or net present value alongside simple ROI. A cumulative three-year ROI is not an annual return.
Step 2: Calculate the Full Software Cost
The advertised subscription price is only part of the investment.
Microsoft’s technology cost guidance includes infrastructure, implementation, support, training, and change management within a broader ownership assessment.
Your software estimate should reflect the costs relevant to your business.
| Cost category | Examples |
|---|---|
| Subscription or license | User seats, modules, annual plans |
| Implementation | Configuration, consulting, workflow design |
| Data migration | Cleaning, mapping, importing, verification |
| Integration | Connectors, development, ongoing maintenance |
| Training | External instruction and staff learning time |
| Administration | User management, reporting, troubleshooting |
| Usage charges | Transactions, storage, messages, API usage |
| Transition and exit | Overlapping subscriptions, export, decommissioning |
For cash-based ROI, include actual additional spending.
For a broader economic calculation, also value relevant internal staff time. For example, if salaried employees spend time implementing the system without extra pay, that is a resource cost even though it may not increase payroll.
Avoid counting the same expense twice if it is already included in an implementation package.
Use Current Commercial Terms
Check official pricing and the proposed contract for:
- Required minimum seats.
- Monthly versus annual commitments.
- Usage allowances and overages.
- Support charges.
- Renewal pricing.
- Cancellation and export conditions.
Use consistent currency and tax treatment throughout the calculation.
Step 3: Identify Benefits You Can Support
Start with changes you can measure rather than a list of attractive features.
Direct Spending Reductions
Examples include:
- Canceling a redundant subscription.
- Reducing paid overtime.
- Lowering external processing fees.
- Avoiding an otherwise necessary contractor expense.
A saving is only incremental if it would not occur without the proposed change.
Do not count a subscription as eliminated while you still need it for another department.
Additional Contribution from Sales
If software helps generate additional sales, use the contribution remaining after the costs required to deliver those sales.
For example:
- Additional attributable revenue: $20,000.
- Associated variable costs: $12,000.
- Additional contribution: $8,000.
The benefit is $8,000 before subtracting the software costs included elsewhere in the model.
Count only the portion reasonably attributable to the software. Increased demand, new staff, pricing changes, or advertising may also explain the improvement.
Fewer Errors and Less Rework
A tool may reduce duplicate orders, billing corrections, or avoidable processing mistakes.
Estimate the change using actual records where available:
Estimated avoided cost = Errors avoided × Average relevant cost per error
Separate cash expenses from internal staff time. If both are included, explain the components.
Staff Time Released
A basic estimate is:
Hours released = Time saved per task × Number of tasks
Suppose a reporting tool saves 15 minutes on 80 reports each month:
0.25 hours × 80 = 20 hours per month
That measures capacity. It does not establish a cash saving.
Step 4: Value Time Savings Carefully
This is one of the most important parts of calculating business software ROI.
If an employee saves time but receives the same salary, payroll has not fallen. The business may benefit through faster service, additional output, or reduced workload, but those outcomes need to be identified.
Use a Clear Realization Assumption
Suppose software releases 20 hours per month and the relevant loaded hourly employment cost is $25.
The theoretical capacity value is:
20 × $25 = $500 per month
If you estimate that only 60% can be usefully redeployed:
$500 × 60% = $300 per month in estimated productive capacity
The 60% is an illustrative assumption, not an industry benchmark. Explain what supports your own estimate.
Avoid Double-Counting the Same Hours
If the saved time produces additional sales already included in the model, do not also count its full labor value as a separate benefit.
Likewise, if reduced overtime already captures the saving, do not count those same hours again as released capacity.
The UK Government’s Digital and Data Benefits framework emphasizes uncertainty around adoption, productivity gains, and cost savings, and recommends testing scenarios. Although written for public-sector appraisal, that discipline is useful when evaluating business software.
Step 5: Calculate ROI Using a Worked Example
Consider a business assessing a new order-management system over 12 months.
All figures below are hypothetical. They are not product prices or promised results.
This first calculation uses cash effects and assumes the benefits begin immediately.
First-Year Cash Costs
| Item | Calculation | Cost |
|---|---|---|
| Subscription | $300 × 12 months | $3,600 |
| Additional support and integrations | $100 × 12 months | $1,200 |
| One-time external setup and training | Fixed amount | $1,200 |
| Total | $6,000 |
First-Year Cash Benefits
| Item | Calculation | Benefit |
|---|---|---|
| Legacy subscription eliminated | $100 × 12 months | $1,200 |
| Paid overtime avoided | $200 × 12 months | $2,400 |
| Additional attributable contribution | $400 × 12 months | $4,800 |
| Total | $8,400 |
ROI Calculation
Net benefit = $8,400 − $6,000 = $2,400
ROI = ($2,400 ÷ $6,000) × 100 = 40%
Under these assumptions, the system produces an estimated first-year cash-based ROI of 40%.
Any internal implementation time or capacity benefits should be shown in a separate, consistently constructed economic assessment.
What If Benefits Start Two Months Later?
Assume recurring costs still run for 12 months, but benefits occur for only 10 months.
Benefits = $700 × 10 = $7,000
ROI = [($7,000 − $6,000) ÷ $6,000] × 100 ≈ 16.7%
The software has not changed. The timing assumption has substantially changed its first-year return.
Step 6: Calculate the Payback Period
ROI describes return relative to cost. Payback estimates how long it takes to recover the initial investment.
When monthly amounts are stable:
Payback period = Upfront cost ÷ Monthly net benefit after recurring costs
Using the immediate-benefit example:
- Upfront cost: $1,200.
- Monthly benefits: $700.
- Monthly recurring costs: $400.
- Monthly net benefit: $300.
Payback = $1,200 ÷ $300 = 4 months
This simplified result assumes steady benefits from the beginning.
If benefits ramp up or spending varies, calculate cumulative monthly cash flow instead. Payback occurs when the cumulative balance first becomes non-negative. If monthly net benefit is zero or negative, this simplified formula does not produce a finite payback period.
Step 7: Test Conservative and Optimistic Scenarios
A single ROI figure can conceal uncertainty.
Vary the assumptions most likely to change: adoption, implementation cost, hours saved, sales contribution, or usage charges.
| Illustrative scenario | Benefits | Costs | ROI |
|---|---|---|---|
| Conservative | $6,000 | $6,600 | −9.1% |
| Base case | $8,400 | $6,000 | 40% |
| Optimistic | $9,900 | $6,000 | 65% |
These are alternative assumptions, not predicted outcomes.
Also identify the break-even requirement. In this example, benefits must reach $6,000 over the year to match the modeled cost.
Ask whether the investment remains acceptable under a realistic downside scenario.
Step 8: Compare Forecast ROI with Actual Results
Before implementation, record a baseline.
Depending on the software, useful measures include:
- Processing time per task.
- Paid overtime.
- Error and correction costs.
- Active usage.
- Subscription expenses.
- Sales contribution.
- Support workload.
Assign an owner to each expected benefit and record where the evidence will come from.
Review results after implementation and at renewal. Use comparable periods and consider seasonality, workload changes, and other business initiatives.
A simple before-and-after improvement does not prove that software caused the entire change. A pilot group or phased rollout can help distinguish its effect.
Common Software ROI Mistakes
Counting revenue instead of contribution. Additional sales also create delivery costs.
Treating every saved hour as cash. Capacity and reduced spending are different outcomes.
Ignoring adoption. A feature provides little value if staff do not use it effectively.
Comparing inconsistent periods. Costs and benefits need the same time horizon.
Double-counting improvements. One workflow change can appear in several benefit categories.
Assigning unsupported values to strategic benefits. Better visibility or customer experience can matter without an invented dollar amount.
Using ROI as the only decision criterion. Reliability, affordability, security, operational necessity, and exit options also matter.
Frequently Asked Questions
1. What is a good ROI for business software?
There is no universal threshold. An acceptable return depends on risk, implementation effort, cash availability, expected useful life, and alternative uses of the money.
2. Should employee time savings be included?
Yes, when clearly labeled and justified. Show whether they reduce spending, create additional contribution, or release productive capacity. Avoid counting the same benefit twice.
3. Can software have positive ROI but still create cash problems?
Yes. Upfront costs may arrive before benefits. Review monthly cash flow and payback alongside ROI.
4. How should an existing software subscription be evaluated?
Compare keeping it with realistic alternatives, including cancellation or switching. Focus on future avoidable costs, future benefits, and transition costs. Past spending that cannot be recovered should not drive the forward-looking decision.
5. Does negative first-year ROI mean the software should be rejected?
Not necessarily. Setup costs and delayed benefits can produce a negative first year. Assess a suitable longer period, downside scenarios, cash requirements, and whether the software fulfills an essential need.
Conclusion
Calculate software ROI by defining a realistic alternative, counting the full relevant costs, and identifying benefits you can support with evidence.
Keep cash savings separate from productive capacity, allow for implementation delays, and test uncertain assumptions. The most useful result is a transparent business case you can measure after purchase and use again when renewal comes around.